For rigorous backtesting, exchange-sourced historical minute or tick data, or a research-grade cleaned dataset with documented point-in-time index membership, beats every other option. Broker APIs and free feeds work fine for casual chart-watching, but they routinely fail on adjustment transparency and historical depth. If you're building or validating a systematic strategy, the one requirement you cannot skip is point-in-time membership with documented corporate-action adjustments. Without it, your backtest is measuring a fiction.
TL;DR:
- Point-in-time index membership data with documented corporate-action adjustments is essential to avoid look-ahead bias in backtests, especially for settlement and consolidation-sensitive strategies.
- Exchange direct feeds provide the highest fidelity but are costly, while commercial vendors offer a cost-effective balance with cleaned, back-adjusted data suitable for most backtesting needs.
- Licensing restrictions often limit redistribution of exchange or consolidated data, making commercial vendors or proprietary datasets preferable for research and strategy validation.
- Handling timestamps accurately and maintaining raw, unaltered copies of data helps prevent silent errors and ensures transparency during reconciliation.
- Backtestmarket provides clean, import-ready minute-bar datasets across multiple assets, tailored for immediate use in trading platforms, with support for ongoing updates and technical queries.
Table of Contents
- Where Does Indices Intraday Data Actually Come From?
- What Do Exchange and Consolidated Index Feeds Actually Provide?
- How Should You Evaluate Commercial Index Data Vendors?
- How Do You Avoid Look-Ahead Bias and Reconstitution Errors?
- Which Integration Format Fits Your Trading Setup?
- How Do You Choose the Right Source for Your Backtest?
- What Does Backtestmarket's Data Actually Cover?
- What Quants Should Prioritize When Sourcing Intraday Index Data
- How Backtestmarket Fits Into Your Data Sourcing Plan
- Where to Verify These Details Yourself
- Sources
- FAQ
Where Does Indices Intraday Data Actually Come From?
Every intraday index feed traces back to one of five source classes, and each one trades fidelity against cost in a different way.
Exchange direct feeds sit at the top of the fidelity ladder. These come straight from the exchange or index provider, carry the least latency, and cost the most. They're built for market makers and institutional desks that need every tick as it prints.
Consolidated exchange services package official index data into a distributor-friendly format. Nasdaq's Global Index Data Service (GIDS) is the clearest example: it standardizes delivery so firms don't need a direct exchange connection to get authoritative index levels.
Commercial vendors sell historical bundles, often already cleaned and adjusted, aimed squarely at backtesting and research rather than live execution. This is where a provider like Backtestmarket operates, alongside institutional-grade platforms such as Bloomberg Terminal, which serves large trading desks at a correspondingly large price point.
Broker and platform APIs (MT4, MT5, and similar) give you convenient access tied to your trading account, but the historical depth and cleanliness vary wildly by broker.
Free or public sources are fine for prototyping a hypothesis, but they typically lack the granularity, history, or documentation a real backtest needs.
Quick tradeoff summary:
- Exchange direct feeds: highest fidelity, highest cost, best for live execution and market microstructure work.
- Consolidated services (GIDS-type): official data, standardized formats, strong fit for index-tracking products and institutional research.
- Commercial vendors: research-grade history, import-ready formats, best cost-to-quality ratio for backtesting.
- Broker/platform APIs: convenient but inconsistent depth, fine for quick prototyping.
- Free/public sources: zero cost, but usually missing adjustments, point-in-time snapshots, or sufficient history.
What Do Exchange and Consolidated Index Feeds Actually Provide?
GIDS-style feeds publish more than a scrolling price. They typically include real-time index ticks, official settlement values, intraday portfolio values (IPVs) for tracking funds, and daily component lists with weightings. Nasdaq's GIDS documentation confirms this scope: real-time levels, settlement values, intraday NAV calculations, and standardized delivery across streaming and cloud APIs.
Delivery method matters as much as content. You'll generally choose among:
- A direct exchange connection (lowest latency, highest engineering overhead).
- A distributor feed reselling the exchange's data under a licensing agreement.
- Cloud-based REST or streaming APIs, often the easiest entry point for a small quant shop.
- Kafka-based streaming for firms already running event-driven infrastructure internally.
Licensing is where a lot of teams get surprised. Exchange and consolidated feeds almost always restrict redistribution and redisplay, meaning you can analyze the data internally but can't republish it to clients without a separate agreement. SLA terms on these feeds tend to be strict on uptime but correspondingly expensive.
Here's the practical rule of thumb: use an exchange or consolidated feed when you need official settlement values or component-level accuracy, such as reconciling a futures-based index series against its cash equivalent. Settlement reconciliation gets genuinely tricky here. CME and CBOT filings describe VWAP-based Fixing Price windows, often calculated over a tight window like 2:59:30 to 3:00:00 CT, with tiered rules kicking in when trades are absent during that window. Miss that detail, and your futures-to-cash reconciliation will show mismatches that have nothing to do with your strategy logic.
For most backtesting work outside of settlement-sensitive strategies, a commercial vendor dataset gets you 90% of the fidelity at a fraction of the licensing complexity.
How Should You Evaluate Commercial Index Data Vendors?
Vendor products generally come in four shapes: raw tick data, cleaned minute bars, back-adjusted futures series, and index-level aggregates built from underlying constituents. Which one you need depends entirely on your strategy's holding period. A minute-bar series is usually the sweet spot for most systematic index strategies, balancing fidelity against file size and processing time, per the granularity conventions Investopedia outlines for intraday trading.
Delivery formats vary by vendor, but you should expect to see flat files (CSV or compressed archives), REST endpoints for programmatic pulls, streaming connections for near real-time updates, and, for platform-specific work, import-ready bundles built for MT4 or MT5. That last category matters more than it sounds. A dataset that requires manual reformatting before it loads into your platform introduces a new place for errors to creep in.
Before you commit to a vendor, check for these attributes:
- A sample file you can actually load and inspect, not just a marketing screenshot.
- Documentation covering adjustment methodology, timestamp convention, and timezone handling.
- A QA report or changelog showing how the vendor handles gaps and corrections.
- A real support channel, ideally with someone who understands the data, not just billing.
Any vendor worth using will disclose known issues upfront: timestamp inconsistencies across data sources, missing bars during low-liquidity periods, and how aggregate index values were adjusted when constituents changed. If a vendor's documentation is silent on all of this, treat that silence as a warning sign, not an accident.
How Do You Avoid Look-Ahead Bias and Reconstitution Errors?
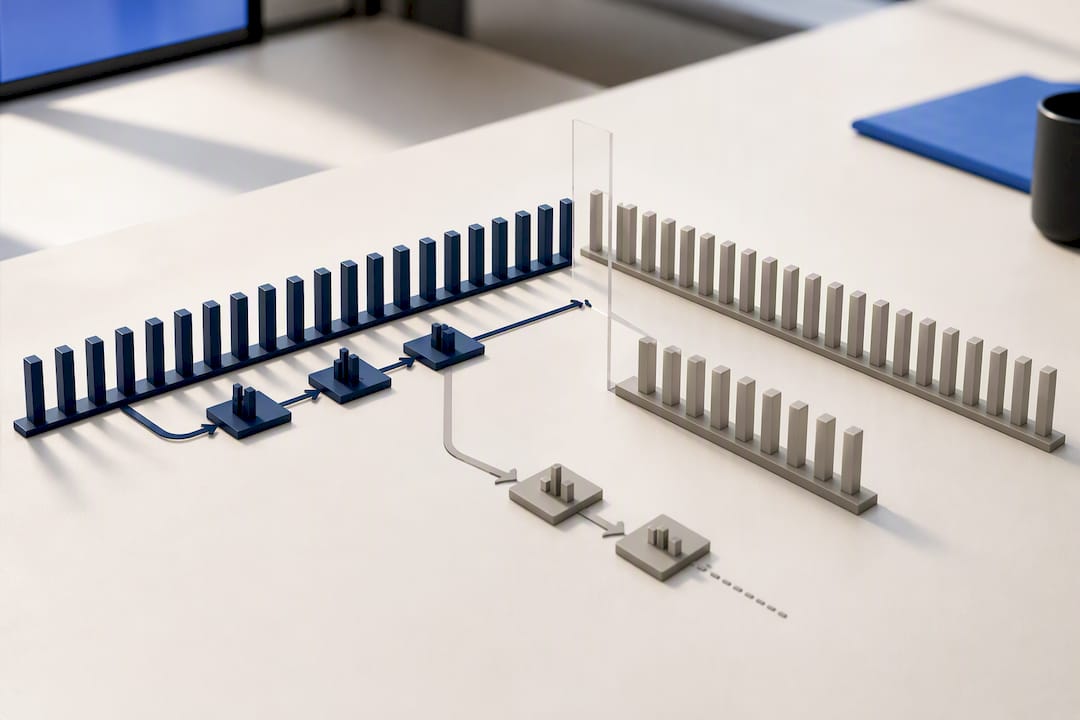
Look-ahead bias creeps into a backtest whenever your strategy has access to information it couldn't have had at that point in time. Index reconstitution is the classic culprit: if you use today's index membership list to test a strategy from three years ago, you're testing against companies that may not have even been in the index back then. S&P Dow Jones Indices' methodology documentation recommends keying data to permanent identifiers like PERMNO or ISIN and using time-gated joins so your backtest only ever sees what the market actually saw on that date.
Here's a practical sequence for handling the biggest data quality risks:
- Pull point-in-time membership snapshots, not just the current index composition, and key every join to a permanent identifier rather than a ticker that can be reassigned.
- Apply documented adjustment rules for splits, dividends, and back-adjusted futures roll dates. Reconcile futures-derived series against cash indexes using the exchange's own settlement and VWAP rules, since subtle mismatches in lead/second-month definitions are a common source of silent backtest errors.
- Handle missing data and zero-volume gaps explicitly. Forward-fill only when you document the rule, and run a sensitivity test to see whether your strategy's results depend heavily on how gaps were filled.
- Log data lineage for every dataset: source, extraction timestamp, transformation steps applied, and any QA checks run before the data reached your backtest engine.
Point-in-time indexing and clear data lineage are the strongest available defenses against look-ahead and reconstitution bias in index research, and they should be treated as non-negotiable requirements when you're evaluating a vendor, not optional nice-to-haves.
Pro Tip: Keep a raw, untouched copy of every dataset alongside your cleaned version. When a backtest result looks too good, the first thing to check is whether an adjustment step accidentally introduced information your strategy wouldn't have had in real time.
Which Integration Format Fits Your Trading Setup?
Your choice of integration format depends on how fast you need the data and how much infrastructure you're willing to run. REST bulk downloads work well for historical backtesting where you pull a large chunk of data once and store it locally. Streaming protocols like WebSocket or Kafka make sense when you need continuous updates for live signal generation. For genuinely low-latency needs, FIX or raw socket connections are the only realistic option, though few backtesting-focused shops need that level of infrastructure.
Timestamp handling causes more backtest bugs than almost anything else. Always store the exchange's native timestamp, normalize everything to UTC for storage and comparison, and pay close attention to Daylight Saving Time transitions, since developer documentation from LSEG specifically flags timezone-adjusted trading windows as a common source of intraday summary errors.
A few operational habits worth adopting:
- Store minute or tick data in a compact, columnar schema rather than sprawling wide tables. It speeds up both storage and query time.
- Run routine reconciliation between your stored data and a fresh pull from the source, catching drift before it corrupts a backtest.
- Validate message integrity with checksums, sequence numbers, and row counts. A gap of a few rows is easy to miss visually but obvious in a count comparison.
Pro Tip: Automate your reconciliation check to run every time you refresh a dataset. A five-minute script that compares row counts and spot-checks a handful of settlement values catches most vendor-side errors before they reach your strategy code. The minute bar data guide walks through what a clean schema should look like for exactly this purpose.
How Do You Choose the Right Source for Your Backtest?
Match your source class to your actual project, not to whatever feed happens to be easiest to sign up for.
- High-frequency or microstructure research needs exchange direct feeds or GIDS-style consolidated data. Nothing else has the tick-level fidelity these strategies require.
- Intraday signal development and systematic backtesting is where research-grade commercial vendor datasets earn their keep, offering clean minute bars with documented adjustments at a fraction of exchange-feed cost.
- End-of-day or lower-frequency analytics can often get by on broker feeds or even free sources, since the bar-to-bar precision matters less at that timescale.
Before paying for anything, run a vendor through this checklist: Does it offer point-in-time historical membership? Can you get a sample file before committing? Is there a delta or changelog report for adjustments? What's the actual support SLA, not the marketing claim? Interactive Brokers' own guide to historical market data sources frames this well: accuracy, latency, historical depth, and cost are the four variables that matter, and no vendor wins on all four at once.
Run a sample import, reconcile it against an official exchange summary, and spot-check a handful of settlement values by hand. If those checks pass, you've done more due diligence than most retail quants ever bother with.
What Does Backtestmarket's Data Actually Cover?
Backtestmarket has built clean minute-bar historical intraday data across forex, metals, bonds, and stock indices since 2014, aimed specifically at the backtesting hygiene problems outlined above. The datasets arrive as complete, all-in-one downloads, ready for immediate import into MT4 or MT5, which removes the reformatting step that introduces so many silent errors in DIY pipelines.
That import-ready structure exists because of a specific problem: quant traders lose time and accuracy when they have to stitch together data from multiple partial sources before a backtest can even run. A single clean download that loads directly avoids that entirely.
A few things worth checking when you evaluate the fit for your own project:
- Whether the historical depth (back to 2014) covers the period your strategy needs to test against.
- Whether the minute-bar granularity matches your strategy's holding period, per the chart granularity conventions most quant desks use.
- Whether direct engineer support answers your specific reconciliation questions, rather than routing you through a generic support queue.
If you're unsure whether coverage matches your needs, the most pragmatic first step is downloading a sample, running it through your own reconciliation checks, and contacting support directly if you spot a gap.
What Quants Should Prioritize When Sourcing Intraday Index Data
The biggest mistake in this space isn't picking the wrong vendor. It's assuming a raw tick feed is automatically trustworthy just because it's granular. Granularity without QA and reconciliation is just more data to be wrong about.
Point-in-time membership, documented adjustment rules, and reproducible data lineage matter more than latency for almost every backtesting use case. A feed that updates every millisecond but can't tell you how it handled a stock split is worse than a slower feed with clean documentation.
Operationally, keep both raw and cleaned copies of everything, automate your reconciliation checks so they run without manual triggering, and schedule periodic data audits even after a dataset has passed initial acceptance testing. Data drifts. Vendors change methodology. Catching that early is cheaper than discovering it after a strategy has already gone live.
— Start
How Backtestmarket Fits Into Your Data Sourcing Plan
Backtestmarket is the practical alternative to stitching together broker exports and free feeds for backtesting: one clean, import-ready download instead of hours reconciling mismatched timestamps and missing bars across five sources.
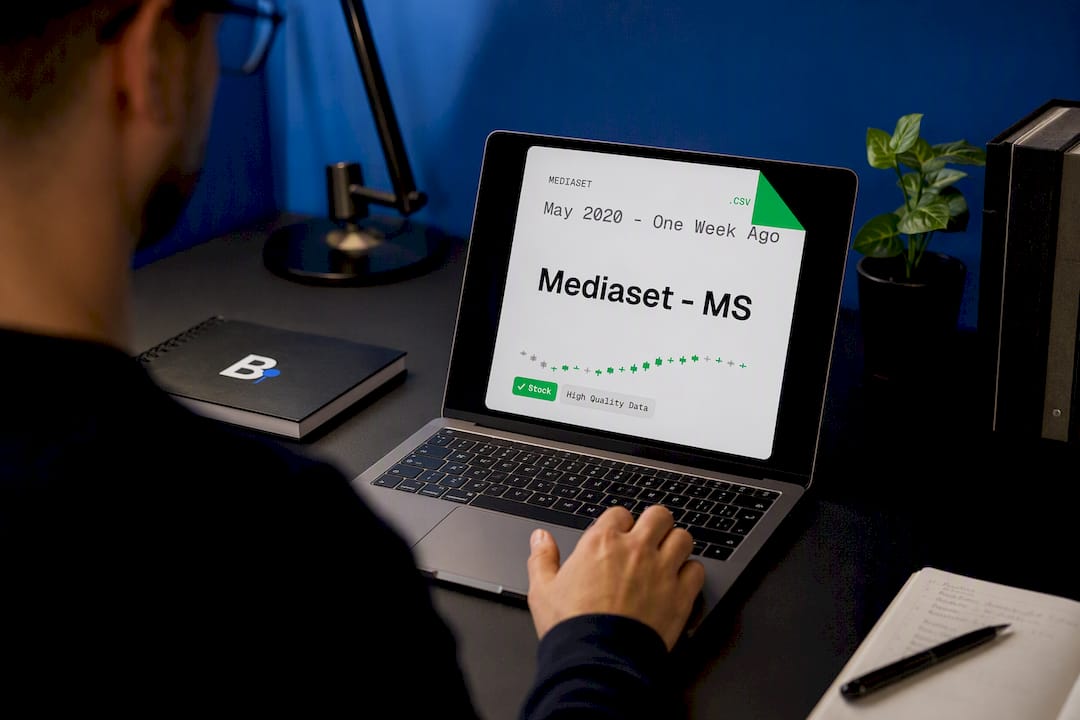
The Historical Data library offers minute-bar datasets across various financial instruments, formatted for direct import into popular trading platforms. If you need ongoing coverage and updates rather than a single download, the Annual Plan runs €119 per year and keeps your dataset current. Traders working with a specific index instrument can also check the Mediaset - MS 1mo dataset directly. Beyond raw data, the site's Expert Advisors and Indicators extend into automated strategy tools once your backtest is validated.
Start with a sample dataset, run the acceptance tests outlined earlier in this guide, and reach out to engineering support directly if your coverage needs go beyond what's listed. Browse the historical data catalog to see what's available for your instrument.
Where to Verify These Details Yourself
- Nasdaq GIDS: official documentation for real-time index levels, settlement values, and component data.
- CFTC filing on CME/CBOT settlement methodology: primary reference for VWAP-based Fixing Price windows.
- Investopedia — Intraday: plain-language reference for intraday chart granularities.
- Interactive Brokers — Historical Market Data Sources: vendor-neutral selection criteria for data sourcing.
- Backtestmarket's MT5 backtesting data guide and MT4 missing data recovery guide for import and troubleshooting specifics.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
FAQ
What Is the Best Source for Intraday Index Data?
For most systematic backtesting, a research-grade commercial vendor dataset with point-in-time membership and documented adjustments offers the best balance of fidelity and cost. Exchange direct feeds and Nasdaq's GIDS are stronger choices only when you need official settlement-level accuracy or true tick fidelity.
What Is the Difference Between Tick Data and Minute Bars?
Tick data records every single trade or quote update, while minute bars aggregate that activity into fixed one-minute intervals. Minute bars are usually sufficient for intraday signal research, since true tick data is necessary mainly for ultra-low-latency or microstructure work.
Why Does Point-in-Time Index Membership Matter for Backtesting?
Index membership changes over time, and using today's constituent list to test a strategy from years ago introduces look-ahead bias. Point-in-time snapshots, keyed to permanent identifiers, ensure your backtest only sees the data the market actually had on any given date.
How Much Does Backtestmarket's Data Cost?
Backtestmarket's Annual Plan is priced at €119 per year for ongoing dataset access and updates, available through the subscription page. Individual historical data bundles are listed on the Historical Data page without a published flat price, so check the product listing for current details.
What Data Format Works Best for MT4 or MT5 Backtesting?
Import-ready minute-bar files that load directly into MT4 or MT5 without manual reformatting reduce the risk of errors during setup. Compressed flat files or complete dataset bundles, like those covered in the MT5 backtesting data guide, tend to be the most reliable format for this purpose.
Recommended
- Nasdaq Intraday Data: Access, Specs, and Practical Use
- Data Snooping Bias: How Researchers and Quants Catch It
- Audit First MT5 Backtesting Data: Gap, Timestamp, Ready to Import
- Minute Bar Data: What Quants Need for Reliable Backtests
Related resources
Explore BacktestMarket's historical data packs to put the ideas in this article into practice.