Blog
Articles, guides et analyses sur le trading algorithmique, les stratégies de backtesting, l'analyse quantitative et la qualité des données.
46–54 of 121 articles
 EN
Quants: 3 Places to Download Verified OHLCV Minute Data
Compact guide for quants to find validated OHLCV minute data: where to download, timestamp and gap rules, validation checks, and ready 1m archives.
 EN
Futures Rollover Methods That Cut Roll Drag for Quants with Minute Bar Tests
Practical, data-driven ways to time futures rolls. Learn to roll by volume, test rules on clean minute-bar data, and reduce roll cost and slippage.
 EN
Fix Live MT5 Expert Advisor Tracking: Watch These 3 Numbers
Practical MT5 EA monitoring: track three metrics, run MAE/MFE diagnostics, and validate live results with BacktestMarket clean minute bar data.
 EN
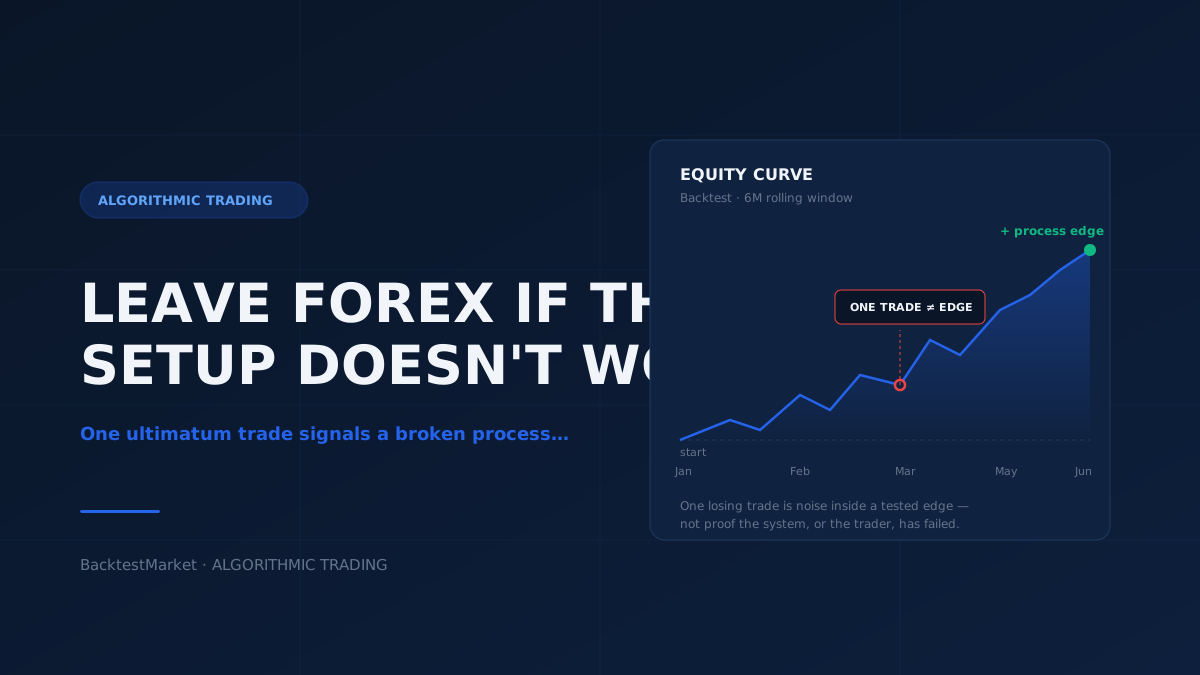
"I'll Leave Forex If This Setup Doesn't Work Out": Why That Mindset Signals a Deeper Problem
When a single trade setup becomes an ultimatum, it's usually a sign the process — not the market — needs fixing. Here's how algorithmic backtesting reframes the all-or-nothing trap.
 EN
Historical Market Data for Quants: 3 Price Bands and When to Buy Once
Map exchange fees to vendor bands and build a realistic budget. Learn three common price bands, hidden licensing multipliers, and when a one-time dataset...
 EN
Quant Traders: One Line Fill Formula to Simulate Minute Bar Slippage
Practical slippage methods for quant traders: a one line per-trade fill formula, sensitivity sweeps, and clean minute bar datasets to trust backtests.
 EN
MT4 Portfolio Backtesting: Export Replay to Find Real Drawdowns
Export, normalize, and replay MT4 backtests to reveal real portfolio drawdown. Use minute bar data and GMT checks to prevent timing errors.
 EN
Three Ways to Run an MT5 Portfolio Backtest With Clean Minute Bars
Three practical ways to turn MT5 exports into a true portfolio backtest, with minute bar audits, normalization steps, and a reproducible checklist.
 EN
99% Modeling Quality for Quants: MQL4 Data Prep Per Year Gap Audit
Make MQL4 backtests reproducible. Import real tick history, use Every Tick with variable spread, then run a per year gap audit and data validation before...