Blog
Articles, guides et analyses sur le trading algorithmique, les stratégies de backtesting, l'analyse quantitative et la qualité des données.
19–27 of 121 articles
 EN
Clean Forex Data: 5 Audit Checks Quants Run Before Backtesting
Make clean forex data backtest ready with five audit checks and a 6 step cleaning workflow. Or use ready to import datasets to skip cleanup.
 EN
Quants: Run This 7 Step Data Audit Before Backtesting on MT4/MT5
A reproducible, audit-first checklist for quants validating MT4/MT5 backtest data. Preserve snapshots, run checksums, classify per-year gaps, smoke-test,...
 EN
Stop Broken Candles in Two Minutes When Importing CSV into MT5
Follow MT5's exact CSV formatting and quick fixes, plus a ready to import M1 dataset to prevent broken candles and bad backtests.
 EN
Protect Your Backtest: 5-Step Audit for Handling Missing Bars
Backtest-safe workflow for handling missing bars: classify gaps, audit patterns, exclude gap-dependent signals or impute past-only, and run sensitivity tests.
 EN
3 Ways to Remove Weekend Bars From Forex Data for Backtesting
Protect forex backtests by removing weekend bars. Learn three practical routes: platform toggles, source cleaning, and plotting fixes, plus when to buy...
 EN
Skip Adapter Work: Cross Asset Data Normalization for Developers
Developer pipeline for cross asset data: harmonize timestamps to ISO 8601 UTC, choose Z score or RobustScaler per series, and cut adapter work with...
 EN
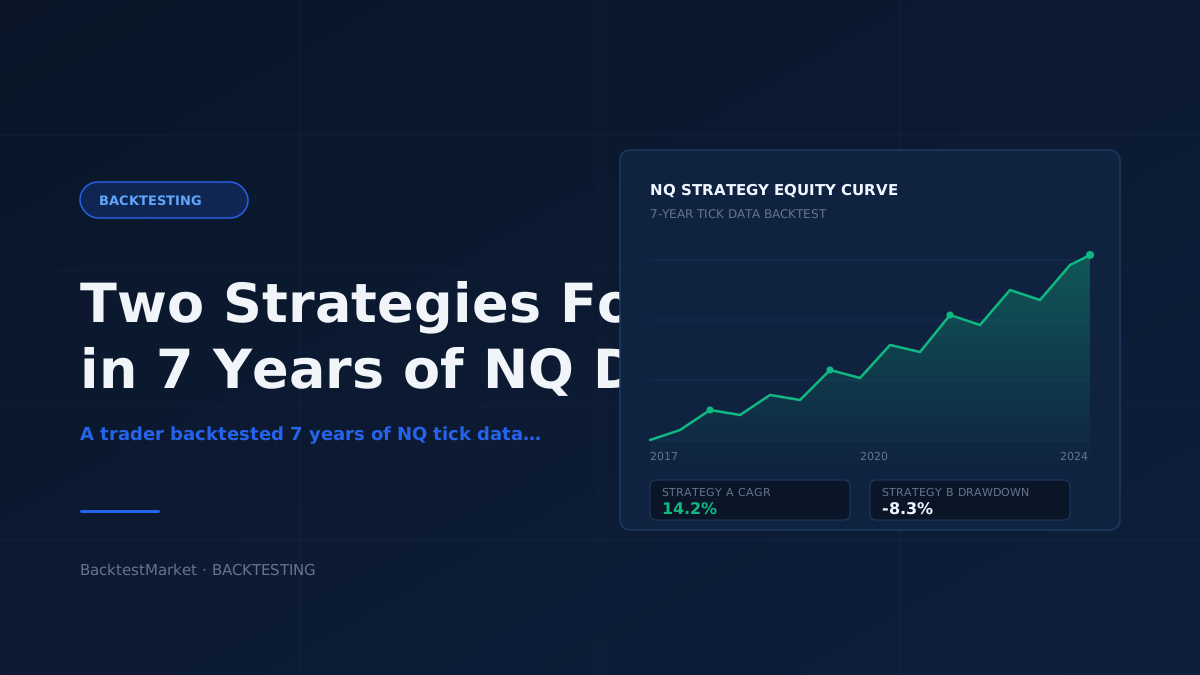
What Seven Years of NQ Tick Data Taught Us About Finding Real Edges
A Reddit trader spent months backtesting seven years of NQ tick data and surfaced two candidate strategies. Here's what that process reveals about how much data you actually need, and how to avoid fooling yourself along the way.
 EN
Avoid Hour Errors: Three Parts to Normalize Time Zones for Developers
IANA aware dev guide: three part fix to normalize time zones and avoid DST and historic offset errors. Python, JS, Postgres recipes.
 EN
Market Data Formats for Developers & Quants: SBE, Parquet, Dollar Bars
A developer and quant primer on market data formats: SBE/FAST feeds, Parquet and CSV storage, tick/volume/dollar sampling, ingestion checks, and...