Blog
Articles, guides et analyses sur le trading algorithmique, les stratégies de backtesting, l'analyse quantitative et la qualité des données.
37–45 of 48 articles
 EN
Avoid Redownloads on Multi GB Bulk Historical Data for Quants
Practitioner guide to multi GB bulk historical data downloads: choose S3 or catalog exports, use wget or aria2c, and verify checksums.
 EN
Audit First MT5 Backtesting Data: Gap, Timestamp, Ready to Import
Run gap and timestamp audits, import clean minute bar or validated tick data, and verify modeling quality to produce reproducible MT5 backtests.
 EN
What Good Data Vendor Support Actually Looks Like
Discover what effective data vendor support entails. Ensure your quant team receives validated data, flexible delivery, and direct engineer access.
 EN
How to Import CSV Data Into MT4 for Backtesting
Learn how to easily import CSV data into MT4 for backtesting. Follow simple steps and troubleshoot common issues to enhance your trading accuracy.
 EN
How to Achieve 99% Modeling Quality in MT4 for Backtests
Achieve 99% modeling quality in MT4 backtests by importing real tick data and ensuring zero errors for trustworthy results.
 EN
Minute Bar Data: What Quants Need for Reliable Backtests
Discover how minute bar data enhances backtesting accuracy for trading strategies. Ensure reliable results with quality, exchange-sourced data.
 EN
Data Snooping Bias: How Researchers and Quants Catch It
Discover how to identify and avoid data snooping bias in research. Learn its implications in drug trials and quantitative trading.
 EN
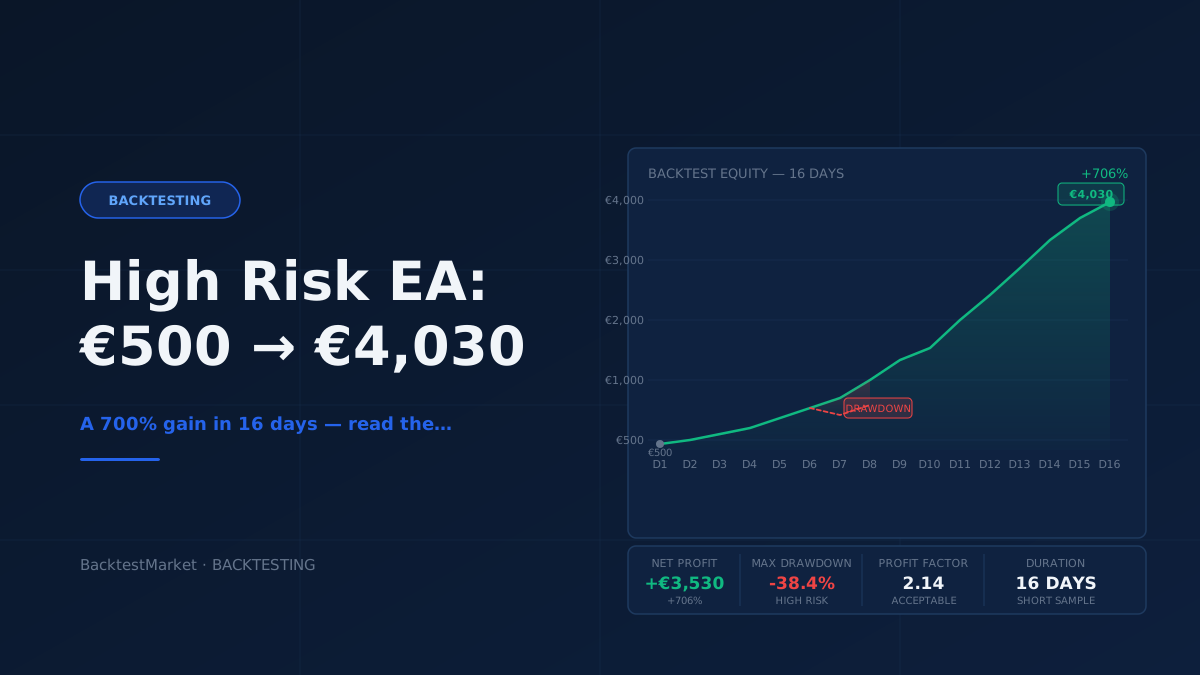
High Risk EA Backtest: €500 to €4,030 in 16 Days — What the Numbers Actually Tell You
A backtest showing a €500 account growing to over €4,000 in 16 days looks extraordinary. Here's how to read past the headline and understand what's really going on under the hood.
 EN
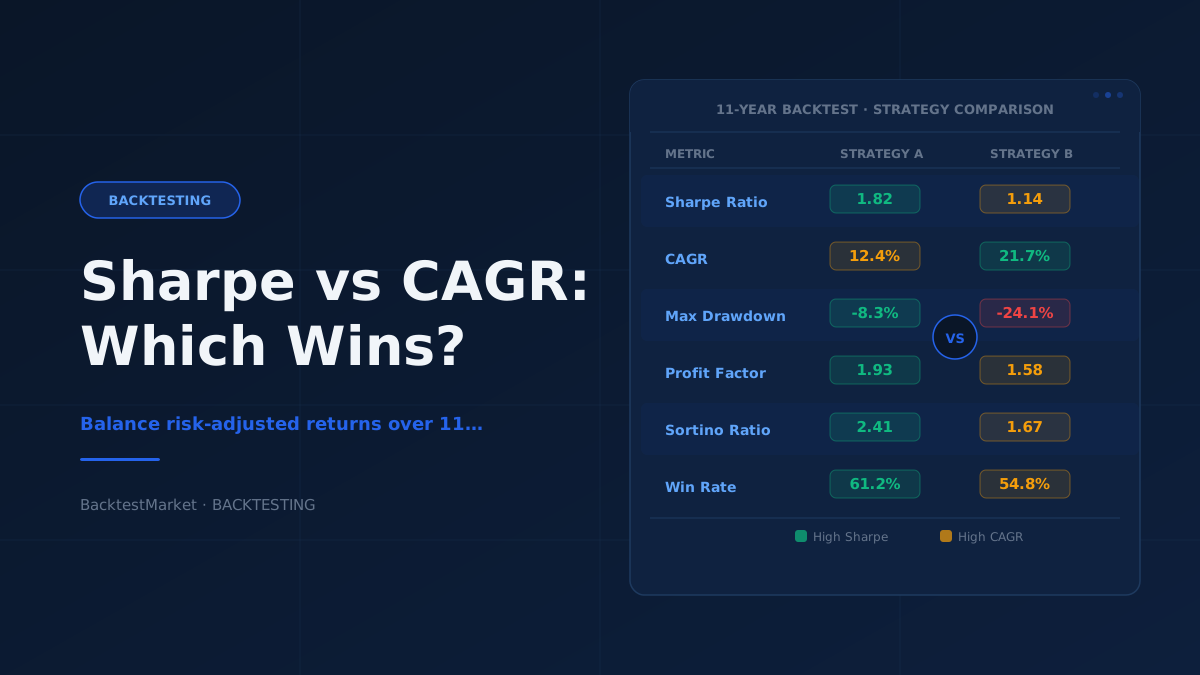
Sharpe Ratio vs CAGR: How to Trade Off the Two Metrics in an 11-Year Backtest
When evaluating a long-term algorithmic trading backtest, Sharpe ratio and CAGR often pull in opposite directions. Here's a practical framework for deciding which one deserves more weight — and when.