Blog
Artikel, Leitfäden und Einblicke zu algorithmischem Trading, Backtesting-Strategien, quantitativer Analyse und Datenqualität.
64–72 of 113 articles
 EN
Data Snooping Bias: How Researchers and Quants Catch It
Discover how to identify and avoid data snooping bias in research. Learn its implications in drug trials and quantitative trading.
 EN
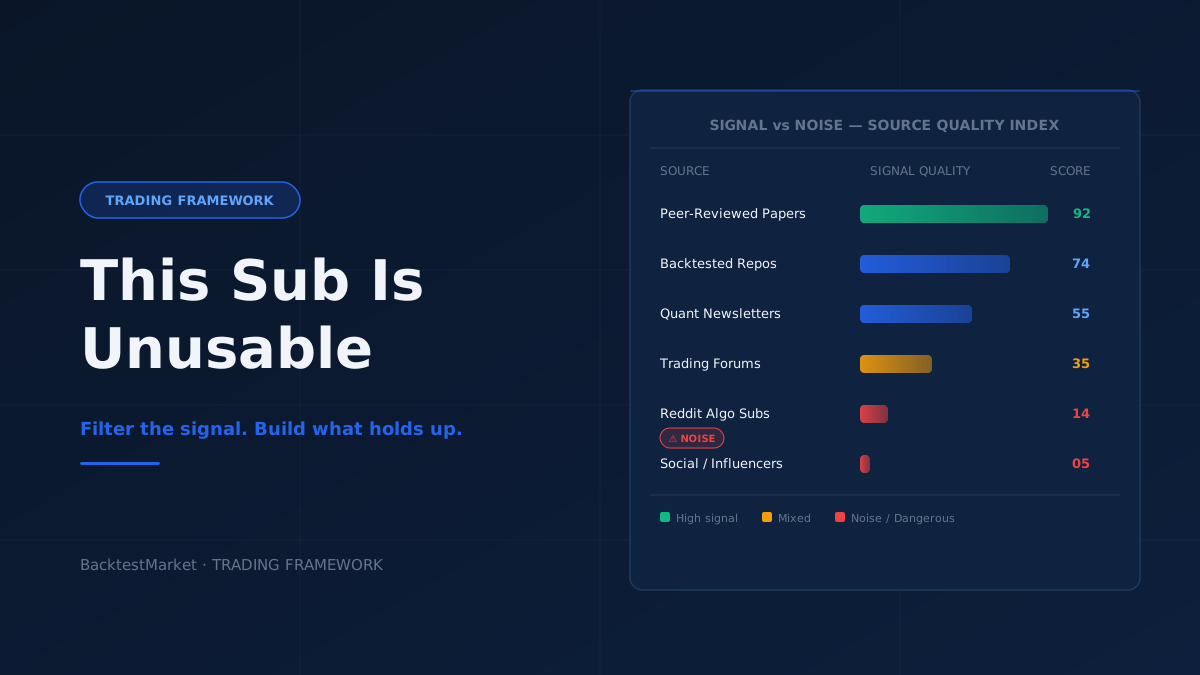
This Sub Is Unusable: Why Reddit Is a Terrible Place to Build a Trading Framework
Reddit's algorithmic trading communities have become increasingly noisy, contradictory, and occasionally outright dangerous for retail algo traders. Here's how to filter the signal from the noise and build a framework that actually holds up.
 EN
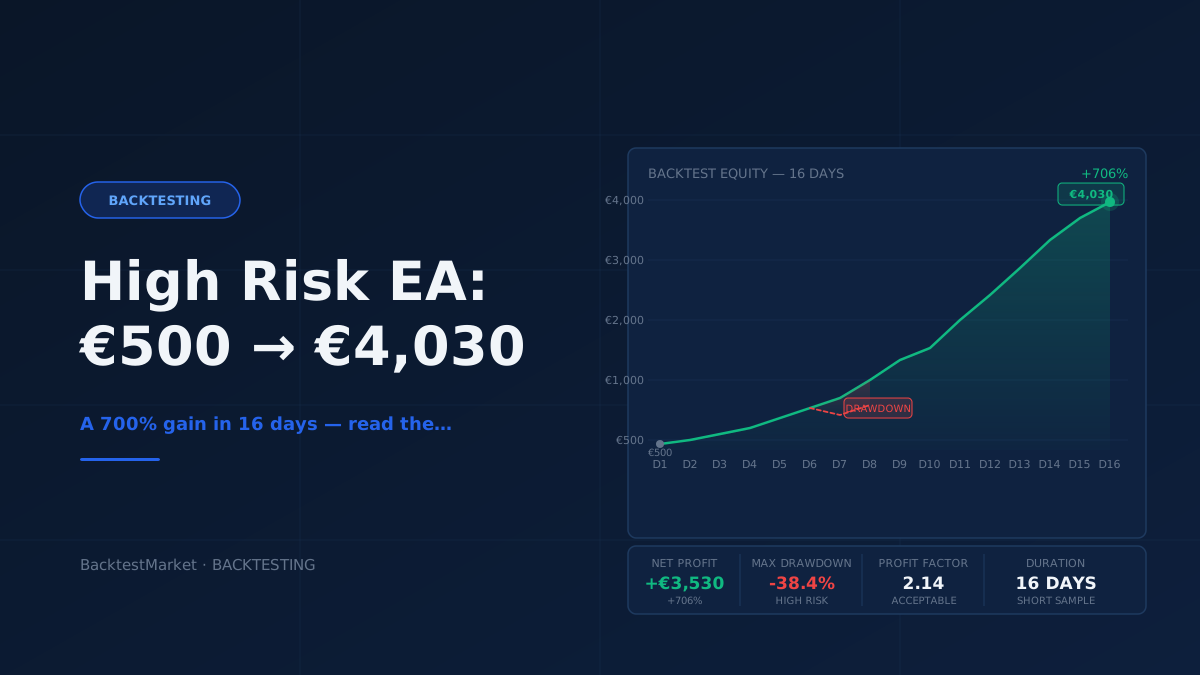
High Risk EA Backtest: €500 to €4,030 in 16 Days — What the Numbers Actually Tell You
A backtest showing a €500 account growing to over €4,000 in 16 days looks extraordinary. Here's how to read past the headline and understand what's really going on under the hood.
 EN
Quant Shop Tier List: How to Evaluate Algorithmic Trading Vendors Before You Buy
Not all quant shops are created equal. This tier list framework helps retail algo traders objectively evaluate algorithmic trading vendors, EA developers, and strategy marketplaces before spending a cent.
 EN
Why Gold Is Reacting Weird (And What Algorithmic Traders Should Do About It)
Gold has been breaking its usual correlations with the dollar, real yields, and risk-off flows. Here's a systematic look at what's changed, why your XAUUSD model may be misfiring, and how to adapt.
 EN
Sharpe Ratio vs CAGR: How to Trade Off the Two Metrics in an 11-Year Backtest
When evaluating a long-term algorithmic trading backtest, Sharpe ratio and CAGR often pull in opposite directions. Here's a practical framework for deciding which one deserves more weight — and when.
 EN
What Is a Good Profit Factor for an MT5 EA?
Profit factor is one of the most cited metrics in MT5 backtesting, but what number actually means your EA is worth trading? This guide breaks down how to interpret profit factor in context.
 EN
Ukraine & Iran Wars: Impact on Financial Markets and Where We Go From Here
Two simultaneous geopolitical crises — Russia's invasion of Ukraine and the Iran-Israel conflict — have permanently altered the risk landscape for stocks, forex, commodities and futures. Here is our analysis and forecast for where each asset class is headed.
 EN
What is Continuous Futures Data and Back-Adjustment
Futures contracts expire — so how do you build a continuous historical price series? We explain the two approaches: raw concatenation and back-adjustment, and when each makes sense for backtesting.