Blog
Articles, guides and insights on algorithmic trading, backtesting strategies, quantitative analysis, and data quality.
37–42 of 42 articles
Data Snooping Bias: How Researchers and Quants Catch It
Discover how to identify and avoid data snooping bias in research. Learn its implications in drug trials and quantitative trading.
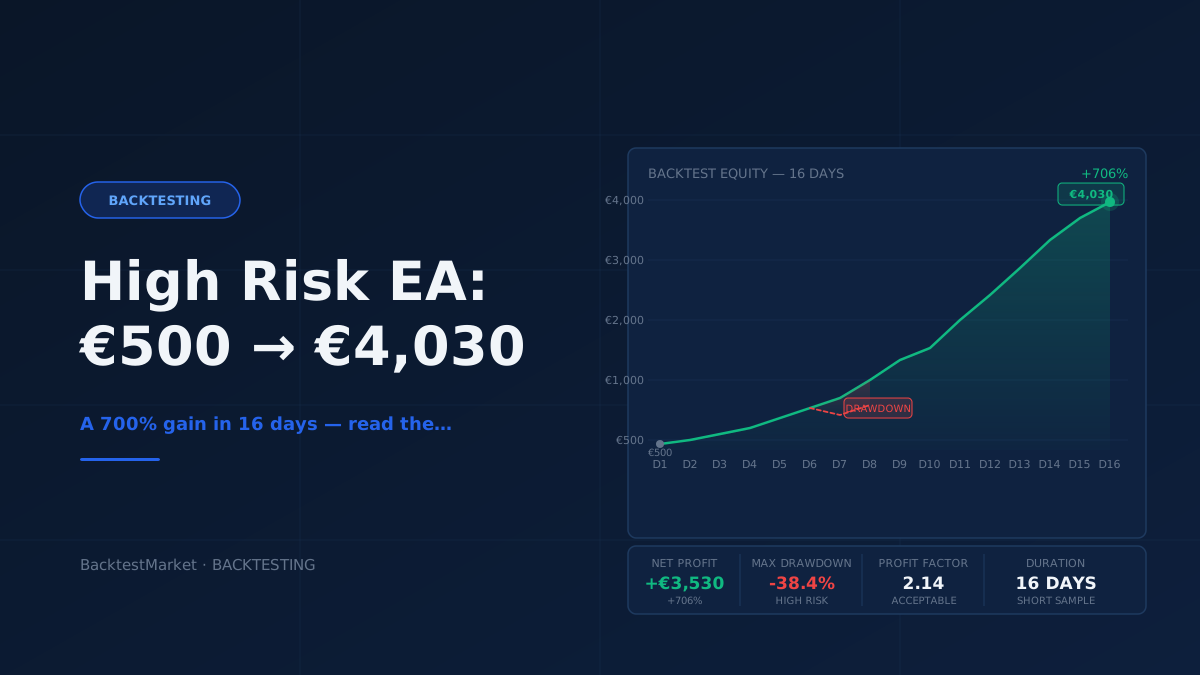
High Risk EA Backtest: €500 to €4,030 in 16 Days — What the Numbers Actually Tell You
A backtest showing a €500 account growing to over €4,000 in 16 days looks extraordinary. Here's how to read past the headline and understand what's really going on under the hood.

Sharpe Ratio vs CAGR: How to Trade Off the Two Metrics in an 11-Year Backtest
When evaluating a long-term algorithmic trading backtest, Sharpe ratio and CAGR often pull in opposite directions. Here's a practical framework for deciding which one deserves more weight — and when.

What Is a Good Profit Factor for an MT5 EA?
Profit factor is one of the most cited metrics in MT5 backtesting, but what number actually means your EA is worth trading? This guide breaks down how to interpret profit factor in context.

How to Manage Overfitting in Trading Systems
Overfitting occurs when a trading strategy describes noise instead of the underlying market relationship. Learn the 4-step methodology to validate your Expert Advisor against 30+ years of data and avoid curve-fitting traps.

Profit or Loss, This Is the Question!
When backtesting in MetaTrader, a candle touching both stop loss and take profit creates ambiguity — which was hit first? The worst-case scenario methodology solves this problem and tests true strategy robustness.