Blog
Articles, guides and insights on algorithmic trading, backtesting strategies, quantitative analysis, and data quality.
10–18 of 42 articles
Clean Forex Data: 5 Audit Checks Quants Run Before Backtesting
Make clean forex data backtest ready with five audit checks and a 6 step cleaning workflow. Or use ready to import datasets to skip cleanup.
Quants: Run This 7 Step Data Audit Before Backtesting on MT4/MT5
A reproducible, audit-first checklist for quants validating MT4/MT5 backtest data. Preserve snapshots, run checksums, classify per-year gaps, smoke-test,...
Protect Your Backtest: 5-Step Audit for Handling Missing Bars
Backtest-safe workflow for handling missing bars: classify gaps, audit patterns, exclude gap-dependent signals or impute past-only, and run sensitivity tests.
3 Ways to Remove Weekend Bars From Forex Data for Backtesting
Protect forex backtests by removing weekend bars. Learn three practical routes: platform toggles, source cleaning, and plotting fixes, plus when to buy...
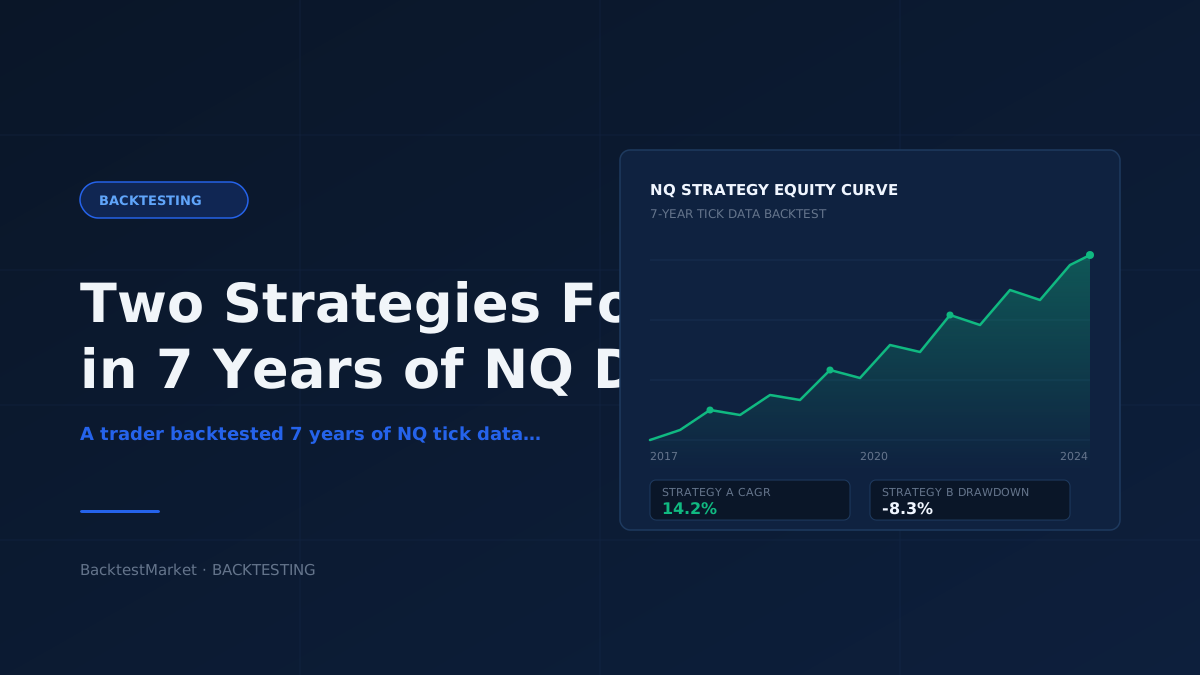
What Seven Years of NQ Tick Data Taught Us About Finding Real Edges
A Reddit trader spent months backtesting seven years of NQ tick data and surfaced two candidate strategies. Here's what that process reveals about how much data you actually need, and how to avoid fooling yourself along the way.
99% Modeling Quality for Quants: MT5 Backtesting Data IS to WFA to OOS
Trust MT5 backtests: use 99% modeling-quality ticks, set realistic costs, run IS to WFA to OOS validation, and speed final checks with a ready-import...
Avoid Look Ahead Bias: Indices Intraday Data Sourcing for Quants
For quants sourcing intraday index data: focus on point in time membership, documented adjustments, and import ready minute bars to keep backtests honest.
Quants: 20,000 Bars Is Roughly 10 Weeks of Intraday History
Quants: convert platform bar caps into calendar time. 20,000 one minute bars is about 10 weeks. Learn when tick data matters and where to get clean minute...
Match Metals Intraday Data to Execution or Backtests for Quants
Match metals intraday data to execution or backtesting. Practical QA checks: timestamps, contract rolls, sample-day audits, and why clean minute bar...