Blog
Articles, guides and insights on algorithmic trading, backtesting strategies, quantitative analysis, and data quality.
46–54 of 115 articles
MT4 Portfolio Backtesting: Export Replay to Find Real Drawdowns
Export, normalize, and replay MT4 backtests to reveal real portfolio drawdown. Use minute bar data and GMT checks to prevent timing errors.
Three Ways to Run an MT5 Portfolio Backtest With Clean Minute Bars
Three practical ways to turn MT5 exports into a true portfolio backtest, with minute bar audits, normalization steps, and a reproducible checklist.
99% Modeling Quality for Quants: MQL4 Data Prep Per Year Gap Audit
Make MQL4 backtests reproducible. Import real tick history, use Every Tick with variable spread, then run a per year gap audit and data validation before...
Reproducible MT4 Backtesting Data Sources That Skip Conversion
Developer-focused MT4 guide to verification checks, CSV import pitfalls, and import-ready datasets. Learn how to avoid timezone, gap, and modeling-quality...
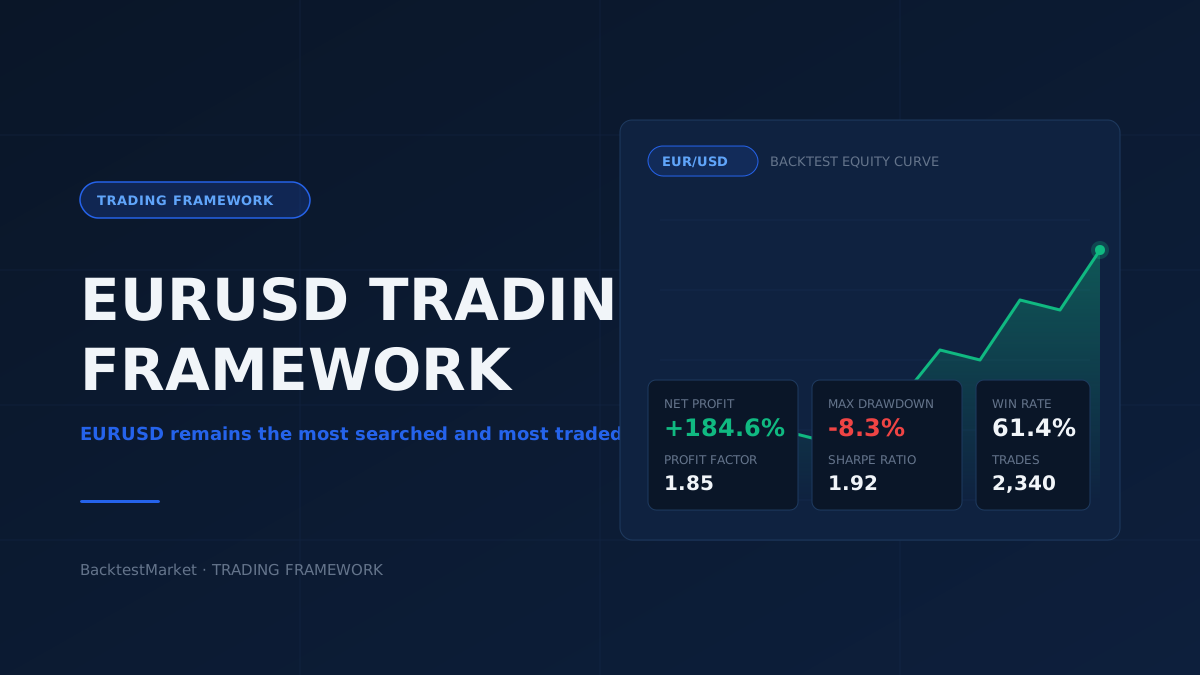
Building an EURUSD Trade Framework: A Backtesting-First Approach
EURUSD remains the most searched and most traded currency pair for a reason. Here's how algorithmic traders can build a structured, backtest-driven framework around it instead of chasing signals.
Stop False Backtests: 3 QA Checks for MT4/MT5 Import Ready Datasets
Stop false backtests: run three QA checks, import one M1 file correctly for MT4/MT5, and use BacktestMarket datasets with timezone tags and checksums.
Avoid Redownloads on Multi GB Bulk Historical Data for Quants
Practitioner guide to multi GB bulk historical data downloads: choose S3 or catalog exports, use wget or aria2c, and verify checksums.
5 Audits Quants Must Run on Outlier Handled M1 Data Before MT4/MT5
Run five audits, verify dataset hashes and annual gap reports, import clean M1 files into MT4/MT5 for realistic reproducible backtests.
Audit First MT5 Backtesting Data: Gap, Timestamp, Ready to Import
Run gap and timestamp audits, import clean minute bar or validated tick data, and verify modeling quality to produce reproducible MT5 backtests.