Blog
Articles, guides and insights on algorithmic trading, backtesting strategies, quantitative analysis, and data quality.
37–45 of 115 articles
5 Minute Import Test for a Data Coverage List Before You Buy
Test a vendor sample for 5 minutes to verify a data coverage list, catch survivorship or timezone gaps, and confirm import readiness.
Stop Broken Backtests: Quants Track Historical Data Updates Like BEA
Practical operations for analysts and quants to keep historical data updates audit-ready: pin versions, watch changelogs, and handle annual revisions...
Avoid Blind Spots by 3 PM: Engineered Intraday Correlation for Quants
Engineered intraday correlation data with estimator guidance and preprocessing to avoid underestimating exposure by 3 PM. Ready MT4/MT5 datasets.

Quants: 3 Places to Download Verified OHLCV Minute Data
Compact guide for quants to find validated OHLCV minute data: where to download, timestamp and gap rules, validation checks, and ready 1m archives.

Futures Rollover Methods That Cut Roll Drag for Quants with Minute Bar Tests
Practical, data-driven ways to time futures rolls. Learn to roll by volume, test rules on clean minute-bar data, and reduce roll cost and slippage.

Fix Live MT5 Expert Advisor Tracking: Watch These 3 Numbers
Practical MT5 EA monitoring: track three metrics, run MAE/MFE diagnostics, and validate live results with BacktestMarket clean minute bar data.
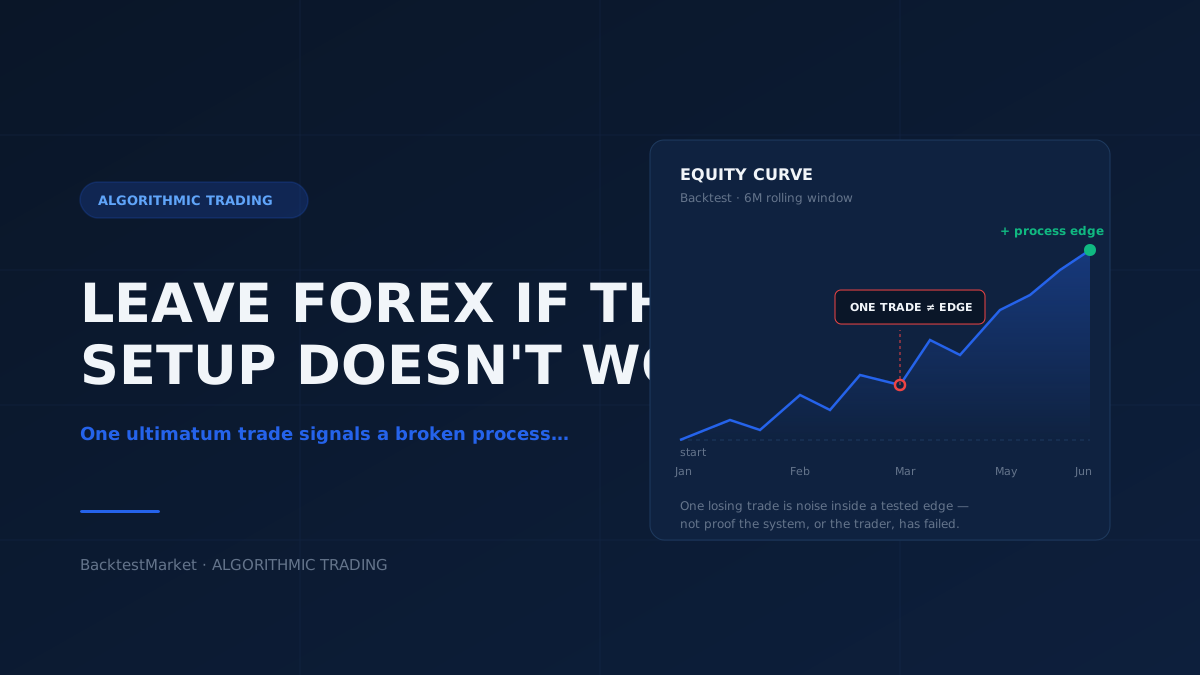
"I'll Leave Forex If This Setup Doesn't Work Out": Why That Mindset Signals a Deeper Problem
When a single trade setup becomes an ultimatum, it's usually a sign the process — not the market — needs fixing. Here's how algorithmic backtesting reframes the all-or-nothing trap.
Historical Market Data for Quants: 3 Price Bands and When to Buy Once
Map exchange fees to vendor bands and build a realistic budget. Learn three common price bands, hidden licensing multipliers, and when a one-time dataset...
Quant Traders: One Line Fill Formula to Simulate Minute Bar Slippage
Practical slippage methods for quant traders: a one line per-trade fill formula, sensitivity sweeps, and clean minute bar datasets to trust backtests.